Rising component prices and elevated baseline specifications threaten to shrink global sub-$200 handset shipments by 40 per cent.
More than 230 million annual sub-$200 smartphone shipments are projected to vanish from the global market between 2025 and 2030, according to Counterpoint Research’s latest Smartphone Shipment Forecast by Price Band tracker. The affordable segment is set to contract by roughly 40 per cent over the period, even as overall global smartphone volumes recover toward 2025 levels by the end of the decade.
This divergence highlights a structural shock stemming from the 2026–2027 market downturn. Soaring memory and chipset costs, rising baseline hardware specifications, and reduced vendor appetite for low-margin products will severely constrain entry-tier device availability. Consequently, consumers face forced choices: upgrading to higher price points, delaying replacements, or turning to pre-owned devices.
The shift risks impeding digital inclusion across emerging economies. In regions where handset pricing remains a critical hurdle to mobile internet access, the shrinking pool of low-cost hardware threatens to slow first-time smartphone adoption and broader internet connectivity initiatives.
Counterpoint Research Principal Analyst Yang Wang noted: “The smartphone market will recover in unit terms, but the affordable segment will not return to its previous standing. The opportunity now shifts toward better-specced mainstream devices and premium products, although higher tiers cannot absorb all the lost volume. The result will be a market that is similar in overall size but materially different in value and competitive profile. There is also a wider connectivity risk, as the loss of affordable new smartphones could make it harder for first-time users in lower-income markets to come online.”
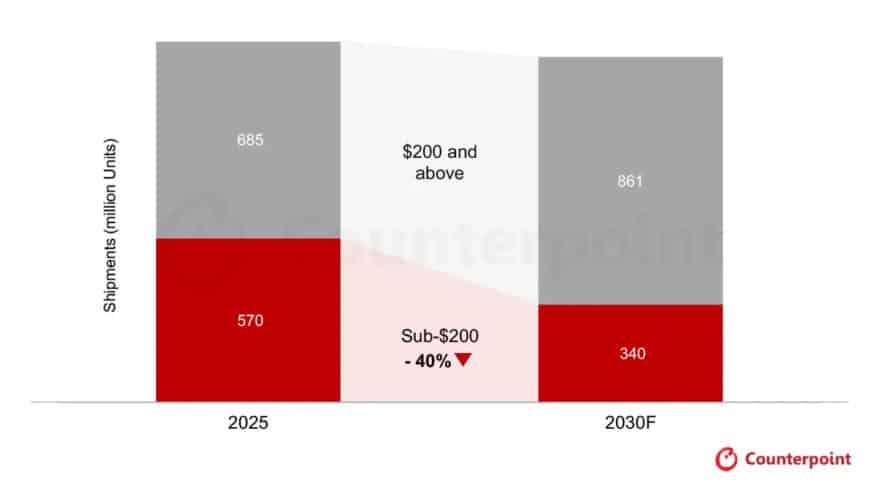
Global smartphone shipments are forecast to recover to roughly 1.20 billion units by 2030, matching 2025 volumes closely. However, sub-$200 device shipments are expected to remain down by around 40 per cent, whereas devices priced at $200 and above are projected to grow by 26 per cent.
The entry-level segment will bear the brunt of this contraction because component prices make up a far larger proportion of the total bill of materials. Consequently, hardware manufacturers have minimal margin flexibility to absorb rising input costs.
Growth trends across price tiers will diverge significantly through 2030. Premium handsets are expected to expand at a compound annual growth rate of roughly 7 per cent, whilst mid-tier and high-tier segments remain largely stagnant.
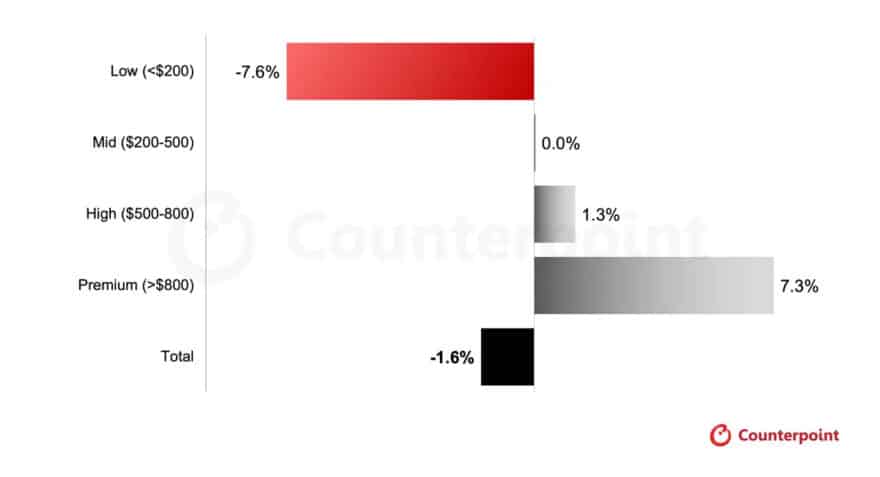
This flatlining in the mid-range indicates that budget buyers are not simply trading up. Instead, market dynamics point to a combination of selective upward migration, extended device holding periods, and permanently lost demand for new devices.
Beyond unit volumes, the contraction presents severe risks for global digital inclusion. In low- and middle-income regions, rising entry-level prices threaten to stall the transition from feature phones to smartphones, impeding internet access for lower-income demographics.
Mitigating this gap will require coordinated industry action, including expanded device financing, trade-in initiatives, targeted subsidies, and tax reforms designed to preserve the commercial viability of basic smartphones.
Premium smartphones are projected to capture an increasing share of global shipments and a dominant proportion of overall market value through 2030, offering the industry its primary engine for revenue growth and hardware innovation. Demand will remain resilient, underpinned by affluent consumer bases, accessible device financing, trade-in schemes, and brand ecosystem loyalty. Furthermore, foldables, advanced camera technology, expanded storage options, and on-device AI capabilities will provide manufacturers with clear avenues to raise average selling prices (ASPs).
The financial benefits of this upward shift will concentrate among vendors with established brand equity, robust hardware-software ecosystems, and sustained retail channel investment. Apple is set to remain the principal contributor to total premium market value globally. Meanwhile, Samsung is well positioned to capture value across both mass-market and high-end tiers, leveraging its industrial scale and portfolio breadth to maintain broad market coverage.
Among Chinese manufacturers, Huawei is expected to lead higher-tier expansion, propelled by its premium flagships, foldable line-ups, and ongoing market recovery in mainland China. Other prominent Chinese brands will find targeted opportunities to enrich their product mix, though their capacity to drive premium unit volume will vary considerably across different regions and retail channels.
A stronger volume recovery is anticipated from 2028 onwards as supply chain constraints ease, retail pricing stabilizes, and delayed replacement purchases from the 2026–2027 downturn are finally realized. However, the post-downturn landscape will be structurally transformed, with the mid-range comprising the bulk of mainstream volume and premium hardware controlling industry profitability.
Form-factor innovations like foldables and edge-AI features will sharpen product differentiation and boost vendor revenues, though neither technology is expected to trigger an isolated, industry-wide shipment supercycle. Towards the end of the decade, the initial commercialisation of 6G-enabled devices should drive an incremental upgrade cycle, accelerating the trickle-down of advanced features into mainstream price tiers.
Ultimately, balancing high-end innovation with accessible entry points into smartphone ownership will remain vital for the broader ecosystem. Ensuring affordable hardware options exist is essential if the benefits of next-generation cellular networks, edge computing, and artificial intelligence are to reach lower-income demographics worldwide.