Despite concerns of overvaluation with investments in AI data centres, the sector has transformed SK hynix’s fortunes.
SK hynix, on Wednesday reported an operating profit of 83.3 trillion won ($62.8 billion) in the July-September period, marking an increase of 632 per cent, largely driven by high demand for memory chips in the artificial intelligence sector.
The South Korean memory chip giant said that it has posted record revenues and operating profits for six straight quarters, from the second quarter last year. However, the earnings fell behind the market expectations.
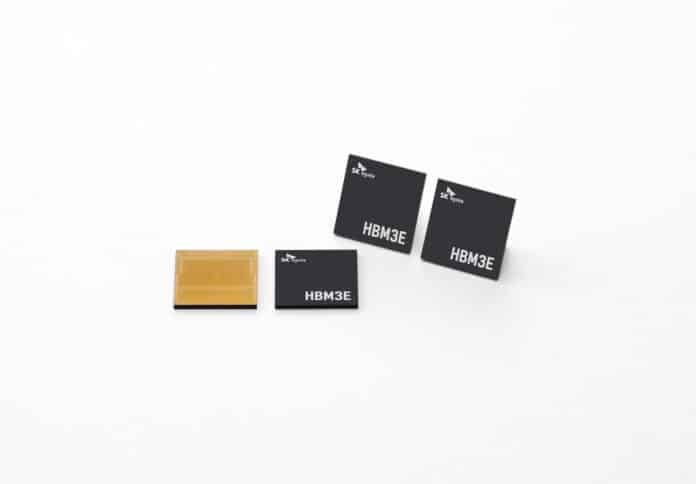
The company is a specialist supplier of high-bandwidth memory to top US technology firms like Nvidia. Despite concerns of overvaluation with investments in AI data centres, the sector has transformed SK hynix’s fortunes. Moreover, chips like DRAM and storage components like NAND, are highly used in everyday gadgets.
Long-term agreements with customers like Nvidia, signals “another phase of price increase in conventional DRAM, NAND and HBM” according to Counterpoint research. This essentially means that quarterly earnings have not peaked yet and are expected to sustain through 2027.
However the company’s share has been under pressure since June, with the stock falling as much as 60 per cent, with investors factoring in quarterly earnings, and weaker AI spending in the coming years, higher competition and company’s own expansion plans dictating price volatility.
Record profits due to AI demand has resulted in investors calling on the company to return more cash through dividends and buybacks. With a $29.8 billion shareholder return programme already concluded, the company announced to return another $44.7 billion to shareholders. Concerns regarding sustainability of the profits of the company in the future are reflected in the share price according to many analysts.